Two Point Five Per Cent and a Lot of Questions: My First Zakat Year on a British Wage
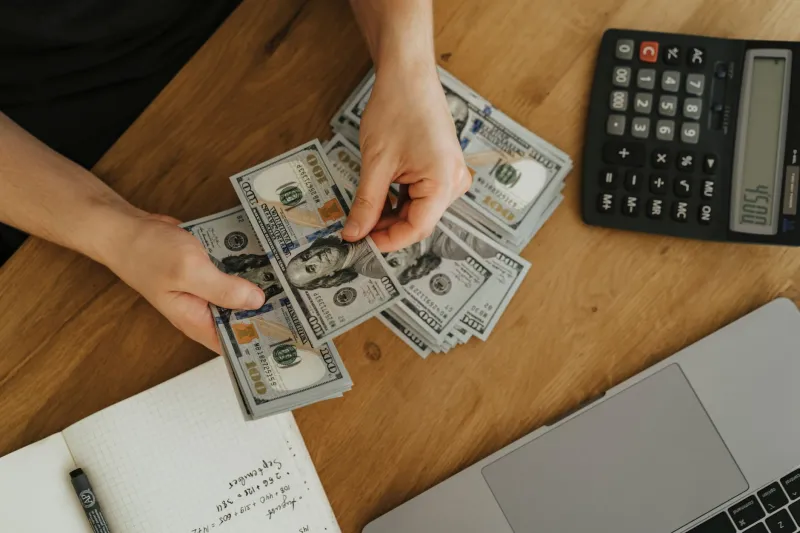
I started my first proper zakat calculation on a rainy Tuesday in November 2026, with a mug of tea going cold and a spreadsheet open on my kitchen table. I had taken shahada earlier this year, and I had spent months learning how to pray, what to say in a mosque and how to explain my new routine to my mum. Zakat felt different. It looked like homework.
That is not because nobody had explained it. Plenty of people had. The trouble was that most explanations began with the beautiful principles and then ended somewhere near a gold nisab figure and a calculator. I understood the idea. Give two point five per cent of qualifying wealth to those who need it. I just did not know what that meant for someone with a workplace pension, a rented flat, a Student Loans Company account and a direct debit to a coffee shop that I am not proud of.
So I did what any sensible British convert does when faced with a religious obligation that involves money. I made a spreadsheet, panicked slightly, and texted three people.
The pay slip, the pension and the bit I ignored
My first mistake was treating my salary as the starting point. Zakat is not income tax. It is not a monthly subscription to being a good person. It is worked out on qualifying wealth that you have held for a lunar year, above a certain threshold, and I had to stop thinking in payslips and start thinking in assets.
That was easier said than done. I had a current account, a savings account I had not looked at since summer, and a workplace pension that I had auto-enrolled into and then ignored. The pension was the bit that confused me most. It is my money in one sense, but it is also locked away until retirement. The people I asked gave me a range of answers, but the common thread was that I should not treat every penny in a pension pot as spare cash sitting in my pocket. Some scholars say pension contributions are not zakatable in the same way as accessible savings. Others have more detailed views. I am not a scholar, and this is not a fatwa. I asked someone trained, wrote down the answer, and kept the workings in my spreadsheet.
My current account was simpler. I added up the balances I actually had on my chosen zakat date, not the money I expected to earn later. I included savings, Premium Bonds, and a small amount of cash I had been given for Eid. I left out my rent because rent is an expense, not hidden treasure. I also left out my coffee habit, which was a relief, because a flat white is not an asset. It is a personality trait with a receipt.
What actually counts, according to people who know more than me
The practical checklist I ended up with looked roughly like this. Cash in accounts. Savings. Investments you can access. Gold or silver, depending on the school of thought. Business stock if you run a business. Money owed to you that you genuinely expect to be repaid. Then you look at short-term debts and liabilities that are due now, and you ask someone qualified how to treat the bigger, messier ones.
My student loan was the messiest. I had assumed I should simply subtract the whole balance and be done with it. A friend gently pointed out that income-contingent student loans do not work like a credit card bill, and that I should not treat it as a simple debt without checking. That was annoying, because I had been looking forward to subtracting a number so large it made my zakat due look like the price of a meal deal. I asked, listened, and used a more sensible approach.
The nisab threshold was the other bit I had to get my head around. It is the minimum level of wealth before zakat applies, often described in relation to gold or silver. I checked the current value, used the figure recommended by people I trusted, and wrote the date at the top of the sheet. The rate itself was the easy part. Two point five per cent. The hard part was honesty.
Student loans, rent and the coffee guilt
Here is the thing nobody warns you about. Zakat has a way of making you look at your spending. Not because every latte is haram, but because you start to see the gap between what you say matters and what your bank statement says matters. I found myself scrolling through months of transactions, wincing at the little purchases, and then feeling oddly defensive about them. I am allowed to enjoy coffee. I am allowed to buy a nice loaf of bread. Zakat is not a punishment for having a life.
But the exercise did change something. I stopped seeing giving as the leftover money after everything else and started seeing it as part of the plan. I put a small amount aside each month so that when my zakat date came round, I was not scrabbling around. I also started being more honest with myself about what I actually needed. Rent in a British city is not cheap. Neither is heating. Neither is the train fare to visit family. The spreadsheet had to reflect real life, not a fantasy version of me who meal-preps every Sunday and never buys a packet of biscuits.
The spreadsheet grows a conscience
When I finally got to the total, I felt a strange mix of relief and embarrassment. Relief because the number was manageable. Embarrassment because I had spent so long avoiding it. I had imagined zakat as a bill, something to get wrong, a test I might fail. What I found instead was a structure. It asked me to be clear about what I had, fair about what I owed, and generous with what remained.
The giving itself was the part that surprised me. I had assumed I would feel virtuous. Mostly I felt connected. I gave part of it to a local mosque fund that supports families in the area, and part to a charity that explained exactly where the money went. That second part mattered more than I expected. Transparency turned the payment from a vague good deed into something I could picture. A food parcel. A school uniform. A heating bill. Zakat is not a tip. It is a right, and the people receiving it are not an audience for my generosity.
Giving as belonging, not just arithmetic
Before this year, I thought belonging was about being seen. Turning up to the mosque. Learning the words. Not getting lost on the way to the prayer hall. Zakat added another layer. It made me part of a community that looks after its own, not in a sentimental way, but in a practical, unglamorous, spreadsheet kind of way. I am not a wealthy person. I am not sure I will ever be one. But I have something to contribute, and that changed how I saw my place in the community.
It also made me less shy about asking questions. I asked about pensions. I asked about student debt. I asked where the money went. Nobody minded. In fact, the people who knew what they were talking about seemed pleased that I cared enough to check. That was a useful lesson for a convert. You are not expected to arrive with every answer. You are expected to ask, learn, and try again next year.
What I would do differently next time
Next year I will pick my zakat date in advance and put it in my phone calendar. I will keep a simple record of my assets and the nisab figure I used. I will ask about anything I am unsure of before the week I need to pay. I will stop treating my pension as either a mystery or a jackpot. And I will remember that two point five per cent is not the whole story. The calculation is the door. The giving is the room. The belonging is what happens when you keep walking through it.
If you are a new Muslim in the UK and zakat feels like a maths exam you did not revise for, start small. Get a notebook. Ask a trusted teacher or imam. Use a calculator. Be honest about your money. And do not let the coffee guilt distract you from the point. The point is not perfection. The point is showing up, doing the sum, and giving what you can with your eyes open.